

Ember - Play Games. Win Big. analysis by Appwee
I approached Ember as a finance app with a game-like presentation rather than as a conventional budgeting or banking tool. That distinction matters immediately. Its store summary promises fast, fun, and thrilling games, while the app’s broader identity sits at the intersection of digital finance and entertainment. My first impression was that it is aimed at people who want a more engaging way to interact with crypto-related activity, not people looking for ordinary expense tracking, bill payments, or a complete replacement for their bank.
That makes the app interesting, but it also creates a responsibility for the user. The playful interface can make financial actions feel lighter than they really are. I found it much easier to enjoy Ember when I treated the game elements as a layer around the experience, rather than assuming that entertainment automatically made every financial decision sensible. If you are comfortable reading screens carefully, checking what an action means, and keeping your expectations realistic, the app has a distinctive appeal. If you want predictable savings tools or a traditional investment dashboard, I would look elsewhere.
From opening the app to deciding what to do next
Ember comes from Ember Fund Inc and is available as a free app for users on a compatible device running at least iOS or Android version 9. It carries a Teen content rating, which feels appropriate for an app that combines games with financial themes, although that rating should not be confused with financial suitability. A teenager may be able to use the interface, but that does not mean every feature or transaction is appropriate for every young user.
The app has been available since January 24, 2019, and its current version is 38.0. That history gives it more of an established presence than a brand-new experiment. Its audience is also substantial: it has passed one million installs, with an average rating of 4.7 from roughly thirty-seven thousand ratings and about two thousand seven hundred written reviews. I would not treat those figures as a guarantee that it will suit me, but they do suggest that the concept has found a real audience.
My recommended starting condition is simple: decide what you want from Ember before tapping through the most exciting-looking parts. Are you looking for a quick game session, a more engaging introduction to crypto, or an app that may connect entertainment with financial activity? Those are different goals. The first can be casual, the second requires patience, and the third deserves the same caution I would apply to any money-related service.
This is also where Ember differs from the usual alternatives. A standard finance app normally begins with balances, categories, charts, transfers, or account history. Ember begins with a more playful mindset. That can lower the barrier for someone who finds conventional finance software intimidating, but it can also make it harder to maintain a calm, analytical frame of mind. I liked the energy, but I would not let the energy choose for me.
Reading the experience instead of rushing through it
When I use an app that mixes games and money, I look for the handoff between the entertaining part and the consequential part. In Ember, that handoff is the key thing to watch. A game-like screen encourages quick decisions and repeated interaction; a financial action deserves a slower pause. My practical tip is to stop whenever the app moves from showing an opportunity or activity to asking me to confirm something with monetary significance.
That pause is not unnecessary caution. It helps separate three questions that are easy to blur together: am I enjoying the game, do I understand the action, and am I comfortable with the possible outcome? Ember is more enjoyable when those questions remain separate. The app’s presentation may make the journey feel smooth, but smooth navigation does not remove the need to inspect the destination.
Another useful habit is to enter with a clearly limited amount of attention and money. I would not open Ember while distracted, during a rushed commute, or when trying to make a serious financial decision quickly. It is better suited to a deliberate session in which I can read labels, review confirmations, and close the app without feeling that I need to chase the next result.
A realistic everyday workflow
Imagine finishing work and wanting a short activity that feels more interactive than scrolling through a conventional finance dashboard. I might open Ember, spend a few minutes exploring the available game-oriented experience, and then decide whether I want to continue or simply leave it there. That is the cleanest everyday use case: the app provides a more lively way to engage with its subject instead of presenting everything as a spreadsheet.
The workflow changes if I decide to move from entertainment into a financial action. I would first identify exactly what the screen is asking me to do, then check the amount, the confirmation wording, and the point at which the action becomes difficult or impossible to reverse. I would not rely on the visual excitement of a reward, progress indicator, or game-like prompt as evidence that the decision is worthwhile.
After confirming an action, I would return to the relevant history or status area and make sure the outcome matches what I intended. This is an important handoff: the app presents an action, I approve it, and then I verify the result. Skipping the final check is how small misunderstandings become larger frustrations. Even if the interface feels simple, my own record of what I did is valuable.
For someone introducing a friend to crypto concepts, Ember could be more approachable than a dense exchange screen. The game framing may encourage curiosity, and the interaction can feel less intimidating than a wall of technical terminology. However, I would explain that approachability is not the same as simplicity in the financial sense. A friendly interface can help someone start learning, but it should not replace independent understanding.
Where the handoffs need the most attention
The first handoff is from curiosity to participation. Ember’s appeal depends partly on making financial interaction feel like something I can explore rather than study formally. That is a genuine strength for newcomers who are put off by traditional finance apps. The trade-off is that curiosity can turn into impulsiveness if the app’s pace becomes more persuasive than my own judgment.
The second handoff is from a game result or activity to an expected financial result. I would keep those ideas mentally separate. Winning a game-like interaction, feeling progress, or receiving a satisfying outcome does not automatically mean that I have made a good financial decision. This is one of the app’s most important psychological boundaries, and it is also the part that a generic store description would not explain.
The third handoff is from the app to the user’s wider financial routine. Ember may be enjoyable as a focused activity, but I would not use it as my only source of financial information. A separate record of deposits, withdrawals, or other relevant activity can make reconciliation easier. This is especially useful if I use several finance apps, because a playful app may not occupy the same role as my bank or a more traditional portfolio tracker.
There is also a social handoff worth considering. If I recommend Ember to a friend, I would recommend the experience, not a particular financial outcome. I would show them how I navigate and how I check confirmations, while making it clear that each person must decide whether the financial side fits their circumstances. That keeps the conversation honest and avoids turning an enjoyable app into unqualified financial advice.
What the free download really means
Ember can be downloaded for free, but the app includes in-app purchases ranging from ninety-nine cents to ninety-nine dollars and ninety-nine cents per item. That range is important because “free” describes the entry point, not necessarily every possible path through the app. Before spending, I would inspect the purchase prompt carefully and decide in advance whether I want to make any optional payment at all.
My strongest practical advice is to create a personal stopping rule before opening the purchase screen. For example, I might decide that I am only exploring the free experience, or that I will not approve a purchase unless I have deliberately reviewed it outside the excitement of the moment. This is not a criticism unique to Ember; it is simply more important when an app combines game-like momentum with money-related decisions.
The purchase range also affects who should skip the app. If you find it difficult to ignore optional purchases in games, or if you prefer finance tools with no entertainment-driven temptation, Ember may create unnecessary friction. A conventional finance app with clearer separation between account management and optional extras would probably be a better fit.
On the other hand, users who enjoy interactive apps and can keep a firm boundary around spending may appreciate the free entry point. I like being able to assess the basic feel before deciding whether the concept belongs in my routine. The sensible approach is to judge the app by the value of the experience, not by the possibility of a big outcome.
How it compares with ordinary finance and crypto apps
Compared with a banking app, Ember feels less practical for everyday money management. I would not choose it to monitor household bills, organize recurring expenses, or replace the calm overview provided by a bank account. Banking software is designed around certainty and administration; Ember is designed around engagement. The two can coexist, but they solve different problems.
Compared with a conventional crypto wallet or exchange, Ember appears more approachable for someone who wants a less technical entry point. A traditional crypto app may offer a clearer market-oriented workflow, with the user actively focusing on assets, orders, balances, and transaction details. Ember’s game-centered approach can feel more inviting, but that invitation may come at the cost of making the underlying financial context less prominent.
Compared with a budgeting app, the difference is even sharper. Budgeting tools help me decide where money should go before I spend it. Ember is not the app I would open to understand whether my monthly spending is under control. If my main goal is financial discipline, I would start with a budget and use Ember only as a separate, limited activity.
Its best comparison is therefore not “better or worse than every finance app,” but “more engaging for a particular kind of user.” Someone who wants finance presented with a game-like layer may find Ember memorable and approachable. Someone who wants sober analysis, predictable planning, or detailed household management will likely be happier with a specialist tool built for that purpose.
The result after a careful session
When I finish using Ember responsibly, the result is less about a single dramatic moment and more about whether the app gave me an enjoyable, understandable experience without pushing me past my own limits. The strongest outcome is discovering a finance app that makes a normally dry subject feel approachable. That can be genuinely useful for a beginner who needs a reason to start paying attention.
The app’s scale and strong average rating suggest that many people connect with this idea. Still, I would interpret popularity as evidence of appeal, not evidence of guaranteed financial success. The result depends heavily on how I use the app: as a controlled way to explore, it can be engaging; as a substitute for research or a shortcut to money, it is the wrong tool.
I also appreciate that Ember can fit into a short session. I do not need to build an elaborate routine around it to understand its appeal. A quick visit can provide entertainment, while a more deliberate session can help me learn how the app connects its game-like presentation with its finance category. The important part is leaving with a clear record of what I did and why.
For a friend who enjoys mobile games, is curious about crypto, and can set firm spending boundaries, I would recommend trying Ember. I would describe it as an engaging introduction and activity, not as a guaranteed route to profit. For a friend who wants a serious investment workstation, a budgeting system, or a bank replacement, I would recommend a different category of app instead.
Where the flow breaks down
The main weakness is the tension between speed and seriousness. Fast interaction is part of Ember’s charm, but finance benefits from slower consideration. Whenever the app’s entertainment rhythm encourages me to act before I have fully understood the consequences, the experience becomes less comfortable. That does not make the app unusable; it means I need to supply the caution that the playful design may not naturally encourage.
Another limitation is role confusion. Because Ember sits in the Finance category while presenting itself through games, a new user may not know whether to judge it as an entertainment app, a learning tool, or a financial service. My answer is that it is best approached as a hybrid. Expecting it to behave exactly like any one of those categories will lead to disappointment.
There is also a practical trade-off in using a hybrid app alongside other tools. I may still need a bank app for ordinary money, a separate source for research, and perhaps another service for detailed records. Ember can be the engaging front door to an interest, but it may not be the complete house. Users who dislike switching between apps should think about that before making it part of a routine.
I would also skip it if I am currently trying to reduce game-related spending, if financial uncertainty is causing stress, or if I tend to interpret entertainment outcomes as predictions about real money. In those situations, the app’s central appeal may work against my goals. A plain, less stimulating finance tool would provide better distance and control.
After weighing the full workflow, my view is positive but measured. Ember Fund Inc has built a distinctive finance app that uses game-like engagement to make its subject easier to approach. The free download, broad audience, and polished current version make it worth exploring for the right person, while the Teen rating and optional purchases are reminders to use it thoughtfully.
My recommendation is to treat Ember as an entertaining, controlled introduction rather than a financial shortcut. Start slowly, separate game excitement from money decisions, verify every important handoff, and keep conventional finance tools available for tasks Ember is not designed to handle. Used that way, it can be a fun addition to a mobile routine. Used without those boundaries, its most appealing feature—the feeling of fast, thrilling interaction—can also become its biggest source of friction.
Gallery
Ember - Play Games. Win Big. Pros and Cons
- Wide selection of casual games in one app
- Simple interface makes games easy to discover
- Rewards add extra motivation to keep playing
- Suitable for short gaming sessions on the go
- Regular challenges can make gameplay feel more engaging
- Rewards may vary by location and eligibility
- Some features may require account registration
- Earning potential can be limited for casual players
- Advertisements may interrupt the gaming experience
- Availability of games and prizes may change over time
Ember - Play Games. Win Big. Frequently Asked Questions
What is Ember - Play Games. Win Big?
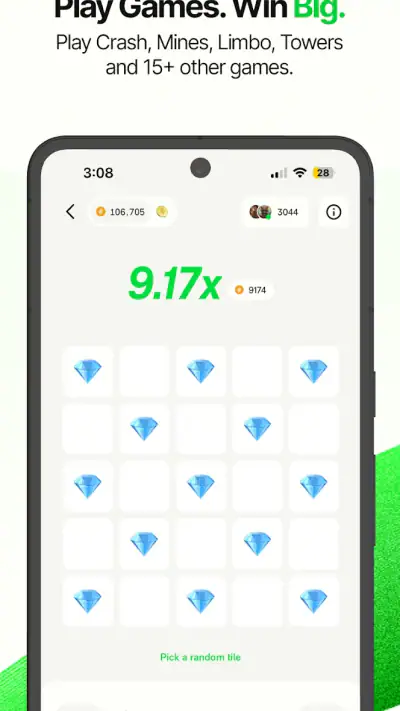
Ember - Play Games. Win Big is a mobile gaming app that combines casual gameplay with opportunities to earn rewards. After installing it, users can browse available games, complete challenges, and track their progress from within the app. The experience is designed to be simple and accessible, although the games, reward options, and availability may vary depending on your location and the current app version.
Is Ember - Play Games. Win Big free to download and use?
The app can generally be downloaded without an upfront purchase, allowing users to explore its games and features before committing financially. However, some games or promotional activities may include optional purchases, advertisements, or other conditions. Before spending money, carefully review the in-app information, payment details, and terms. A free download does not necessarily mean every feature or activity is completely cost-free.
How do rewards and winnings work in Ember?
Ember typically lets users earn points, prizes, or other rewards by playing supported games and completing qualifying activities. The exact earning rules, minimum withdrawal requirements, and available reward methods can change, so it is important to read the instructions shown in the app. Rewards should not be considered guaranteed income, and some offers may have eligibility restrictions, verification steps, or processing delays.
Is Ember - Play Games. Win Big available on Android and iPhone?
Availability depends on the platform, region, and the current distribution of the application. Android users should check the official Google Play listing, while iPhone and iPad users should look for an official App Store version. Avoid downloading modified APK files or unofficial copies from unknown websites, since they may contain security risks. Always verify the developer name, permissions, ratings, and recent reviews before installing.
Is Ember safe for children and does it require personal information?
Parents should review Ember’s age rating, privacy policy, and terms before allowing a child to use the app. Because reward-based services may request account details, contact information, device permissions, or identity verification for certain activities, users should understand how their data is collected and shared. If the app involves purchases or prize-related features, parental controls and spending limits are also recommended.














